Strategy Robustness
Path Dependence and Drawdown Uncertainty
- Published
- 30 JUL 2026
- Reading
- 1 MIN
- Status
- DEMONSTRATION ENTRY
A single historical path is one draw. Resampling return sequences gives a distribution of drawdowns rather than one number.
DEMONSTRATION ENTRY — synthetic data only. No real strategy is represented.
One path is one sample
The maximum drawdown reported by a backtest is a property of the order in which returns happened to arrive. Reshuffling or block-bootstrapping the same returns produces a wide range of plausible drawdowns.
Method sketch
- Take a vector of per-period returns.
- Resample in blocks to preserve short-range dependence.
- Compute the drawdown statistic on every resampled path.
- Report quantiles, not a point estimate.
Reading the figure
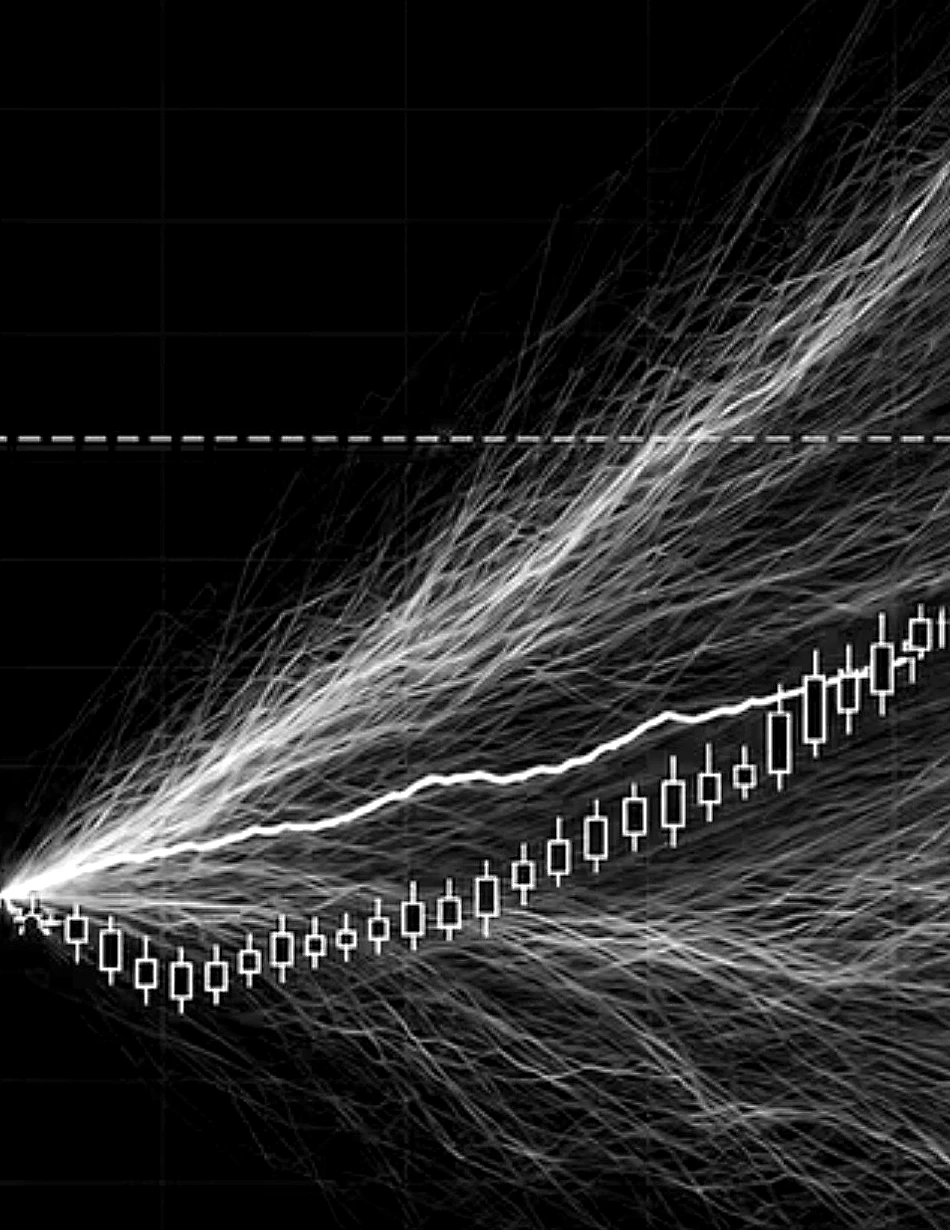
The fan below is generated from a zero-drift random walk with arbitrary volatility. It illustrates dispersion only.
- Median end
- 98.4
- 5–95% range
- 70–140
- Median max DD
- -20.6%
- 95th pct max DD
- -37.1%